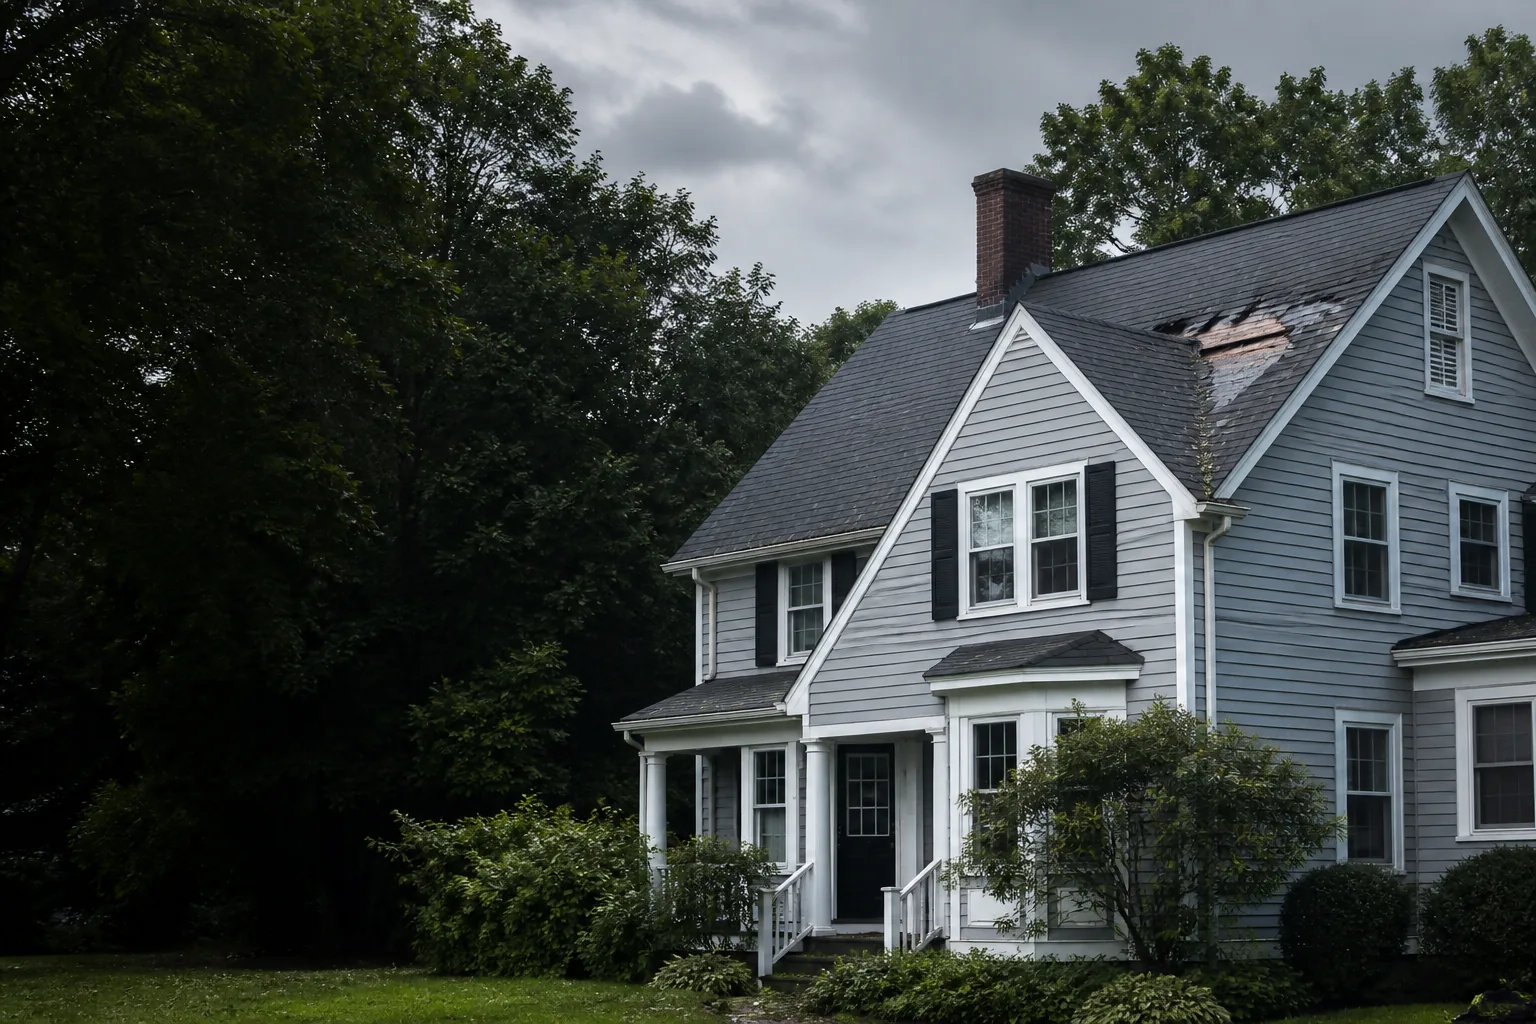
Building Damage
Rooms, roofs, siding, framing, mechanical systems, and finish materials affected by the loss.
Residential Public Adjusting Services
We help homeowners document damage, review claim materials, prepare the loss, and communicate with the insurance company.
Residential Public Adjusting Services
A residential loss can involve structural components, finishes, personal property, temporary repairs, and mitigation work at the same time. Each part should be recorded clearly so the claim tells a complete, organized story.
We review the damage and current claim status, then help connect photographs, measurements, estimates, receipts, and policy information to the issues the insurer is evaluating.
Claim Documentation
Rooms, roofs, siding, framing, mechanical systems, and finish materials affected by the loss.
Damaged household contents, available purchase records, condition notes, and replacement information.
Mitigation reports, temporary repairs, invoices, drying records, and related photographs.
Measurements, contractor proposals, material details, and differences between competing estimates.
How We Help
We discuss the loss, the current claim status, and the questions you want answered.
We inspect visible conditions and identify areas that may require closer documentation.
We review the policy, endorsements, deductibles, and the insurer's stated position.
We organize photographs, measurements, inventories, estimates, and supporting records.
We prepare and present the documented claim and communicate with the insurance company.
We address scope and valuation questions while working toward a policy-based resolution.
Common Claim Issues
An initial estimate may not include every affected room, material, or repair step.
Coverage may depend on how the damage happened and what the policy says.
Contractor scope and insurer scope may differ on quantities, methods, or materials.
Household items can be overlooked when the building damage receives most of the attention.
Service Areas
Connecticut properties range from coastal homes and urban multifamily buildings to older inland houses and newer subdivisions. Construction, access, materials, and the cause of loss can all change what needs to be documented.
Explore our Connecticut service areas or review a specific claim type to see how we approach fire, water, storm, and broader property losses.
Related Claim Help
Frequently Asked Questions
We review residential claims involving fire, smoke, water, storms, structural damage, contents, and denied or potentially underpaid losses. Whether a loss is covered depends on the policy and facts.
Yes. We can review an existing claim, the insurer's estimate, your documentation, and the current status to identify the next practical steps.
No. Bring whatever you already have. We can explain which additional estimates or records may help support the review.
Personal property can be an important part of a residential claim. We help organize available inventories, photographs, receipts, and condition information.
Any fee arrangement should be explained in a written agreement before services begin. Ask about the applicable fee and scope during your claim review.
Tell us what happened, what has been documented, and where the insurance claim stands today.